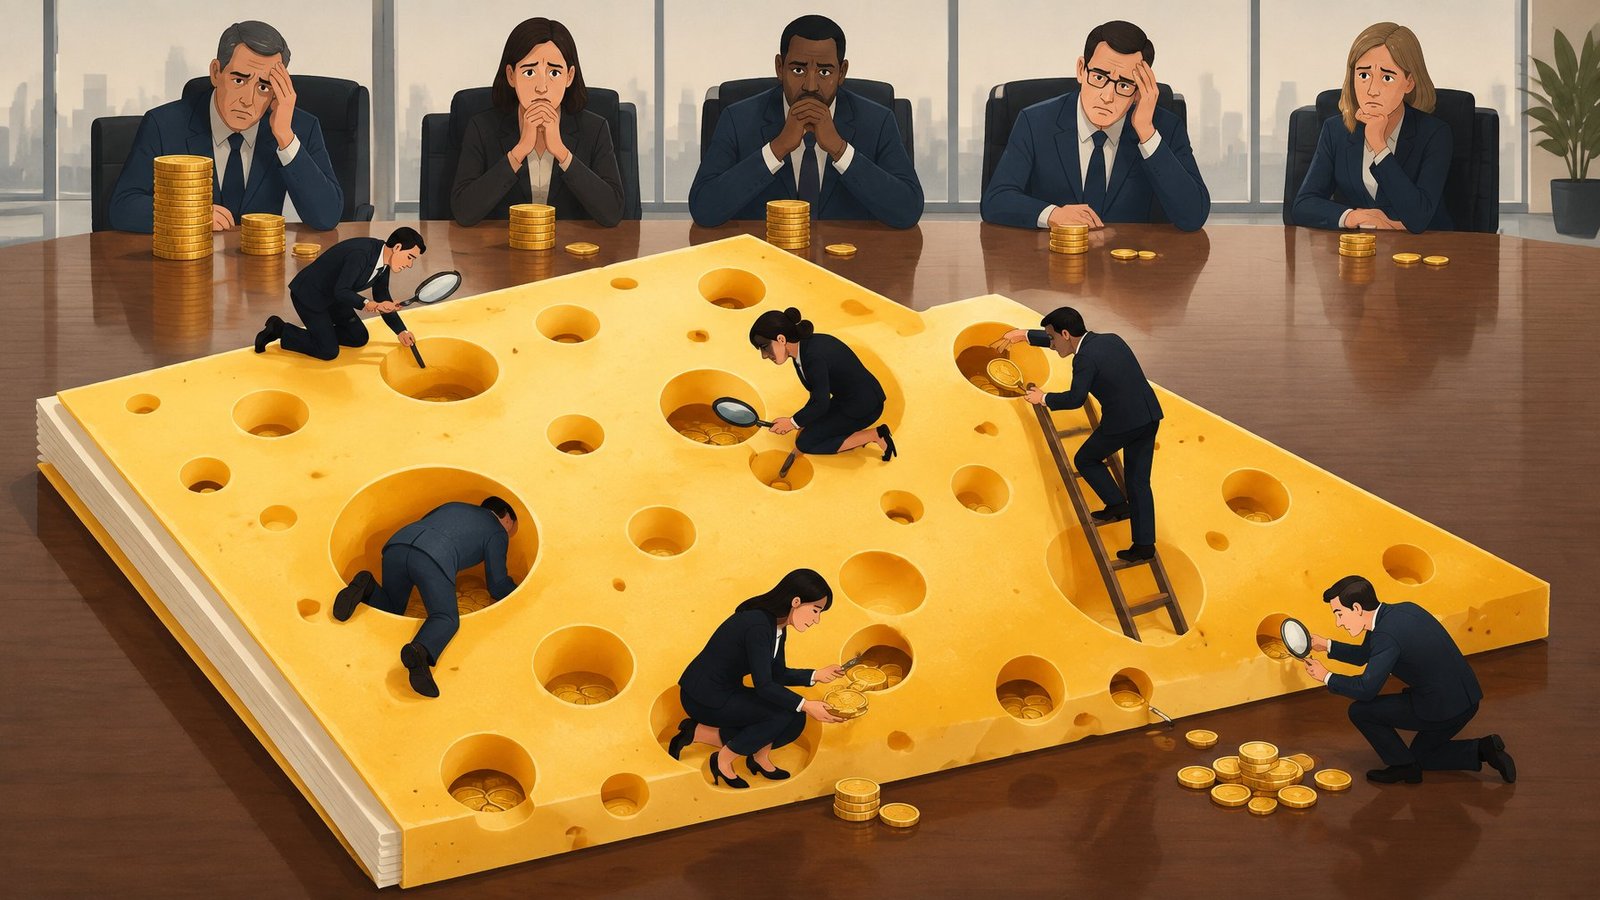
Corporate deal lawyers are supposed to save their clients money by writing airtight contracts. A study of the booming market for leveraged loans finds the opposite: standard loan agreements remain riddled with gaps, and top law firms earn huge fees hunting for loopholes after the fact.
The paper, “Swiss Cheese Contracts: The Costs of Creative Lawyering”, is by Stephen J. Choi, Mitu Gulati, Matthew Jennejohn and Robert E. Scott, law faculty at New York University, the University of Virginia, Brigham Young University and Columbia University. It was posted to SSRN on August 14, 2025 as NYU Law and Economics Research Paper No. 25-20.
The Serta playbook
The authors start with Serta Simmons, the mattress maker. In 2020 a group of its lenders gave the company new money in return for moving their own loans ahead of other lenders in the repayment queue, using an “open market purchase” clause in the loan contract. The excluded lenders were pushed down the line.
Such deals are known as liability management transactions, or LMTs, and the press calls them “creditor-on-creditor violence”. A Texas bankruptcy court approved the Serta deal in 2023. On December 31, 2024, the Fifth Circuit Court of Appeals reversed it, but by then lawyers had devised many other techniques, from “drop-downs” to “double dips”.
Contracts that never got fixed
Economic theory predicts that after a shock like Serta, lenders would rewrite their standard contracts to close the hole. The authors checked by examining over two thousand leveraged loan credit agreements from 2018 to 2024.
The share requiring open market purchases to be offered to all lenders equally rose from 3% to 9% between 2020 and 2021, then slipped back to around 3% in 2022 and 2023. As of the end of 2023, none of the agreements contained broad bans on LMTs or a general good-faith duty among lenders.
Interviews with more than 50 market participants told the same story. “The notion that LMTs are being uniformly blocked is just not accurate at all,” one said. One interviewee put the legal fees from a single LMT at more than $100,000,000.
Why the gaps persist
The authors argue that standard loan documents are treated as fixed “market” artifacts. Drafting lawyers, whose fees are paid by the borrower, focus on small redlines rather than redesigning hundreds of pages, so expertise migrates to the back end, where restructuring specialists earn large fees finding and exploiting loopholes.
They also point to an erosion of norms after Serta, when aggressive private equity sponsors and their lawyers faced little reputational harm, and to a credit glut since the financial crisis that shifted bargaining power to borrowers.
Dispersed, short-term investors in the loans have little reason to pay for better contracts. The authors conclude that borrowers are stuck in a “second-best world” where keeping the ambiguous language that invites LMTs is their best strategy, despite the high costs that follow.
Study Details:
- Title: Swiss Cheese Contracts: The Costs of Creative Lawyering
- Authors: Stephen J. Choi, Mitu Gulati, Matthew Jennejohn, Robert E. Scott
- Journal: NYU Law and Economics Research Paper No. 25-20 (SSRN working paper)
- Publication Date: August 14, 2025
- Link: https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5391281