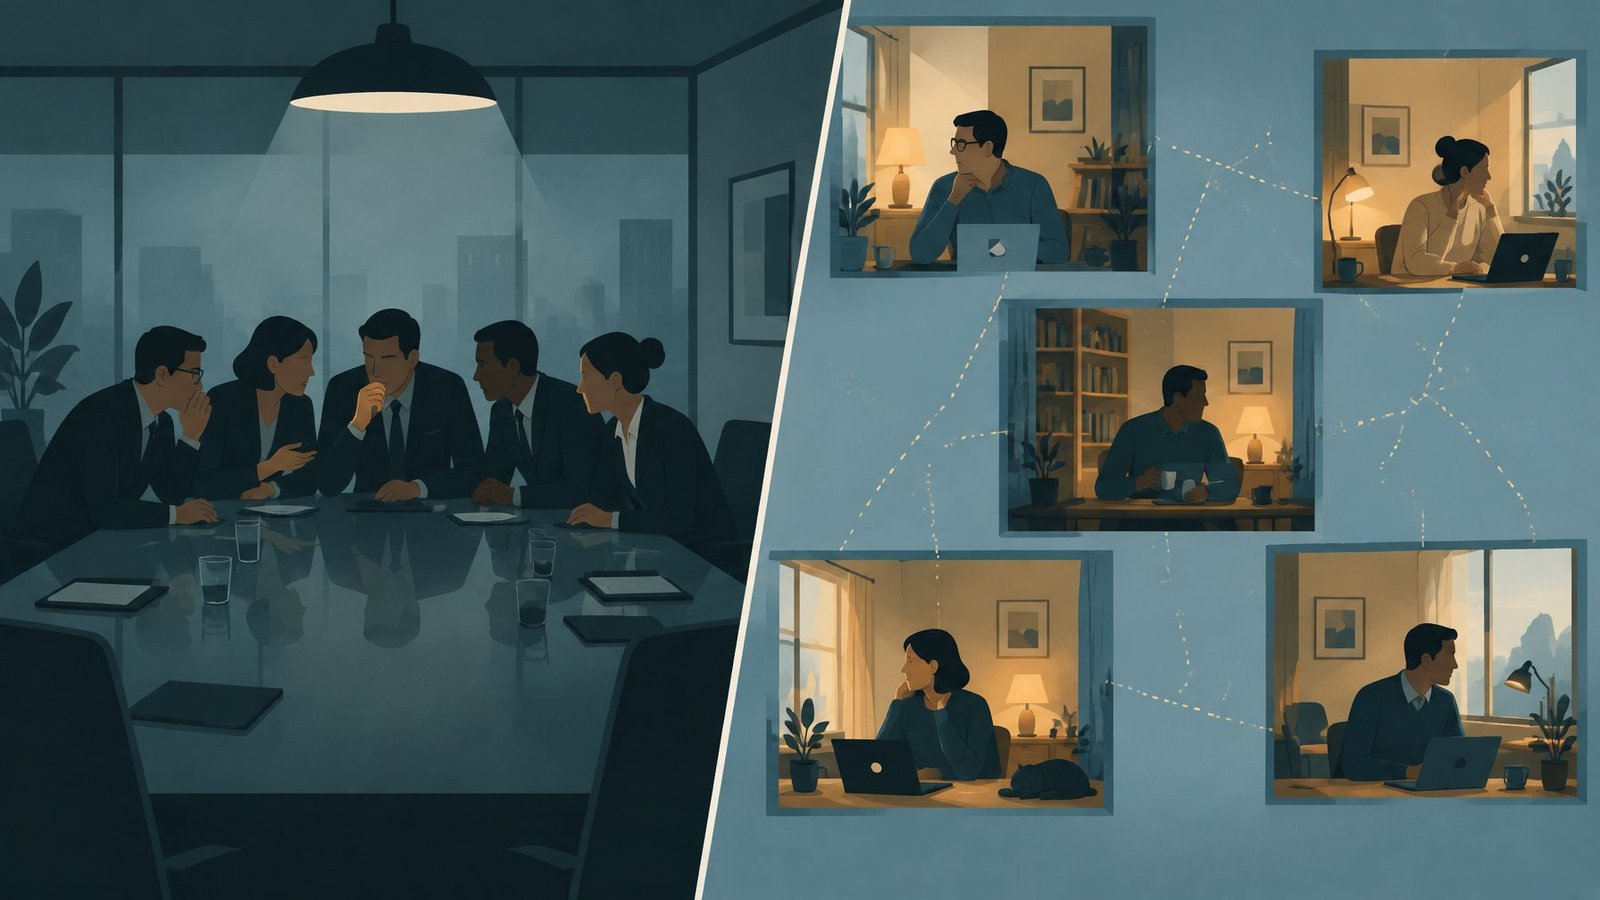
Accounting fraud usually takes a team, and remote work made teams harder to assemble. After the pandemic pushed offices online, US public companies whose staff could more easily work from home saw sharp declines in financial misconduct.
The study is by John Barrios of the Yale School of Management and Jessie Jianwen Guo and Yanping Zhu of New York University’s Stern School of Business. It was released as NBER Working Paper No. 34417 in October 2025.
Measuring who could work from home
The authors built a new firm-level measure of work-from-home feasibility. They applied occupation-level teleworkability scores to each company’s mix of jobs, drawn from LinkUp job postings and Revelio Labs workforce records built from LinkedIn profiles, using 2019 values.
This lets two firms in the same city differ, for example a New York investment bank and a logistics company. Firms that scored higher before COVID were in fact more likely to adopt remote or hybrid work later.
Misconduct was measured as Rule 10b-5 securities class actions alleging accounting manipulation, plus restatements classified as fraudulent, intentional or tied to an SEC investigation, dated to the year the misconduct was committed. The main sample covered 9,552 firm-years from 1,489 companies between 2017 and 2024.
A large drop, and not just in detection
Using a difference-in-differences design, the authors found that moving from the first to the third quartile of remote-work feasibility lowered the likelihood of misconduct by about 2 percentage points, compared with a sample average of 2.7%. There was no sign of differing trends before 2020.
The drop also appeared in discretionary accruals, a continuous measure of earnings manipulation that does not depend on anyone catching it. Monitoring of financial reporting did not weaken at the high-feasibility firms, and among sued firms, an interquartile rise in feasibility shortened the time to a lawsuit by about 28%.
The authors also checked whether pandemic damage explained the pattern. Firms with higher feasibility did not show lower crash risk or higher returns after 2020, and placebo tests with a fake 2018 start date found nothing.
Where collusion got harder
The decline was larger at firms with strong pre-COVID teamwork cultures, and it showed up in lawsuits naming multiple defendants rather than single individuals. It was concentrated in firms with effective internal controls, where overriding safeguards is more likely to require collusion.
It was also bigger at firms whose employees rated leadership and culture poorly before the pandemic, which the authors read as a sign that those firms leaned on informal, in-person networks.
The authors acknowledge that differences between strong and weak governance regimes could not be statistically distinguished. Their conclusion is that fraud behaves like a team activity, so the way a company organises its people shapes how easily insiders can cook the books together.
Study Details:
- Title: Fraud at a Distance? How Remote Work Shapes Financial Misconduct
- Authors: John Barrios, Jessie Jianwen Guo, Yanping Zhu
- Journal: NBER Working Paper No. 34417
- Publication Date: October 2025
- DOI: 10.3386/w34417